
Key facts at a glance
- The US Treasury has published a draft outbound investment rule that would expand the existing Outbound Investment Security Program.
- The proposal would widen restrictions on American capital flowing into chips, artificial intelligence and other sensitive technologies.
- It implements the COINS Act, passed in the 2026 defence bill, and covers chips, AI, quantum technology, supercomputing and hypersonic systems.
- Treasury used authority under the act to add biotechnology to the list.
- The countries named as countries of concern include China, Hong Kong, Macau, Cuba, Iran, North Korea and Russia; Venezuela is also named, though Treasury says it does not meet the draft definition today.
- The draft replaces the term AI systems with super intelligence systems, citing a 29 September executive order by President Trump.
- Some deals would require notification to Treasury; others would be prohibited. Violations could lead to civil penalties and forced divestment.
- The Federal Register is due to publish the draft on 26 October, with written comments due by 7 December.
A wider screen for outbound capital
The US Treasury has proposed a rule that would broaden the reach of Washington’s outbound investment controls, adding new limits on American money flowing into advanced chips, artificial intelligence and other sensitive technologies. The draft, published on Thursday, is designed to strengthen the existing Outbound Investment Security Program and to prevent foreign adversaries from using US capital to develop technologies that could threaten US national security.
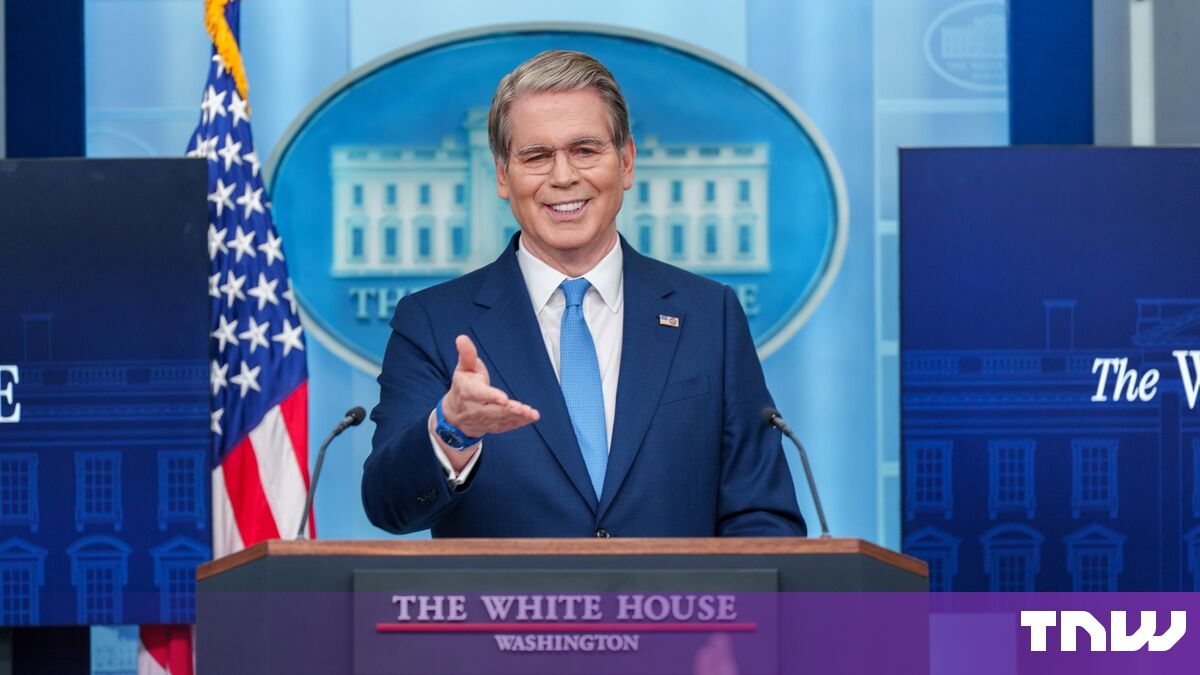
Treasury Secretary Scott Bessent framed the proposal as a security measure rather than a broad economic restriction. Speaking at a White House press briefing in Washington on 28 May 2026, Bessent said the proposed regulations would strengthen the existing programme to prevent adversaries from using US investment to develop critical technologies that threaten US national security.
The rule targets China, Russia, North Korea and other countries of concern. It does not create a blanket ban on all investment in those economies. Instead, it builds a tiered system in which some transactions must be reported to Treasury and others are prohibited. That structure is intended to give the government visibility into sensitive capital flows while blocking deals considered most dangerous.
From a 2023 order to the COINS Act
The outbound investment programme began in 2023. That year, then-President Joe Biden signed an order that limited some US investment in Chinese chips, quantum computing and AI. The initial programme was narrower in scope and focused on a smaller set of transactions. The new draft goes further by carrying out the COINS Act, which Congress passed in its 2026 defence bill.
The shift from an executive-order programme to a statutory framework matters. A law passed by Congress gives the regime a more durable legal foundation and can make it harder for future administrations to unwind. It also gives Treasury clearer authority to define covered sectors, set notification requirements and impose prohibitions. The draft is the first detailed attempt to translate that statutory authority into an operational rule.
Under the proposal, US investors would have to tell Treasury about some deals. The rule would ban others. The distinction is likely to become a central compliance question for venture capital firms, private equity investors, corporate development teams and asset managers with exposure to sensitive technology sectors. Investors will need to determine whether a transaction falls into a notify category, a prohibited category or neither.
Sectors covered and the biotech addition
The law names five core sectors. They are chips, AI, quantum technology, supercomputing and hypersonic systems. Treasury used its power under the act to add biotechnology. That addition expands the rule beyond the digital and hardware domains that dominated earlier debates and brings another area of strategic technology into the screening framework.
The inclusion of biotechnology is significant because it sits at the intersection of national security, public health and commercial innovation. US officials have grown increasingly concerned about sensitive biological data, advanced research tools and dual-use capabilities. By adding biotechnology, Treasury signals that the outbound investment screen is not limited to semiconductors and algorithms. It is intended to cover a broader set of technologies that could shape military, intelligence and economic power.
The five statutory sectors already cover much of the frontier technology landscape. Chips are the foundation of computing and military systems. AI is increasingly embedded in surveillance, logistics, weapons and decision-support tools. Quantum technology could transform computing and cryptography. Supercomputing supports advanced modelling and research. Hypersonic systems are a priority for military modernisation. The draft’s sector list therefore reflects a security agenda that spans both commercial and defence applications.
Countries named in the draft
The list of countries also grows. Beside China, including Hong Kong and Macau, the draft now names Cuba, Iran, North Korea and Russia, according to Treasury’s fact sheet. It also names Venezuela under Nicolás Maduro. But the same document says Venezuela does not meet the draft’s definition today.
That caveat is important. It suggests Treasury is trying to preserve flexibility. The fact sheet names Venezuela, but the operative definition may not yet capture it. That gap could be closed later through changes to the rule or through a determination that conditions have changed. For investors, the caveat creates a distinction between political signalling and immediate legal obligations.
The inclusion of Hong Kong and Macau alongside mainland China reflects the view that capital can move through those jurisdictions and that technology transactions there may raise the same security concerns. The broader country list also shows how the outbound investment programme is being aligned with a wider set of sanctions and export-control measures aimed at adversarial states.
From AI systems to super intelligence systems
The draft swaps the term AI systems for super intelligence systems. Treasury cites President Trump’s 29 September executive order, which renamed AI as super intelligence. The change is not merely semantic. It could affect which systems fall inside the rule and how investors assess their exposure.
Treasury would widen its ban on investing in these systems, the fact sheet said. Investors would lose the current option to simply report such deals. That shift raises the stakes for transactions involving advanced AI development. A deal that might previously have been disclosed to Treasury could now be prohibited outright.
The terminology change also raises questions about definitions. Super intelligence is a contested concept, and the draft will need to explain how Treasury identifies covered systems. Investors will want clarity on whether the term covers only speculative future systems or also current frontier models and the computing infrastructure used to train them. The answers will determine how broadly the ban applies.
Enforcement, penalties and divestment
Breaking the rules could bring civil penalties up to the maximum under the International Emergency Economic Powers Act. Treasury could also force investors to sell. Those enforcement tools give the programme teeth. They also create risk for investors who proceed without careful diligence.
The possibility of forced divestment is particularly significant for private capital. It means a transaction could be unwound after the fact, creating financial losses and reputational damage. Civil penalties add another layer of deterrence. The combination is intended to make compliance a board-level concern rather than a back-office formality.
Christopher Pilkerton, Treasury’s assistant secretary for investment security, said the proposed regulations are designed to address risks that can arise when foreign adversaries try to benefit from US investment in key technology sectors. His comment underscores the programme’s logic: the concern is not only where money goes, but what the money enables.
Comment period and timing
The Federal Register will publish the draft on 26 October. Written comments are due by 7 December. Final rules will follow and set the start date. The timeline gives investors, trade groups and technology companies a window to seek changes before the rule becomes binding.
The comment period is likely to focus on definitions, sector boundaries and the burden of notification. Investors may ask Treasury to clarify how it will treat indirect investments, fund structures and minority stakes. Technology companies may seek more detail on the scope of the super intelligence category and the biotech addition. The final rule will determine how broadly the programme reaches.
China’s countermove and the export-control debate
The move comes six days after China proposed its own controls on exporting advanced AI models and chip designs. That timing highlights how investment rules and export controls are becoming linked instruments in the technology competition between Washington and Beijing. Both sides are trying to control not only goods and software but also capital and know-how.
Last week, Pentagon technology chief Emil Michael said that export controls could curb AI labs. His comment points to a broader debate about whether restrictions on technology flows can slow the development of advanced AI or simply push innovation elsewhere. The outbound investment rule adds another layer to that debate by targeting the capital that funds sensitive research and development.
The draft is not yet final. Its scope could change after the comment period, and the start date has not been set. For now, the proposal signals a widening of US curbs on China AI and chip deals and a more expansive approach to screening American capital in sensitive technologies. The final rules will follow and set the start date.
Source: TNW | Government-policy News